APR for financing brand new TRD Off Road?

How long you finance is really up to your personal situation. I am one that is inclined to pay cash, but if the interest offer is under 3% I find financing to be economically a better call. remember your loan is simple interest and money earned through investments is compound. So if you borrow at 3% and earn 3% on the money you would have used due to the magic of compounding interest you'll make more money on your money than you pay to use the banks money. if you get a better return, even more money. that's just math and economic truth.

Part two, length of loan, I prefer not to have any car financed that is not also under warranty. So my wife's car is a 2013 under warranty till august of 2020 (unlimited Mileage) it will be paid off "naturally" before the warranty expires. the 4Runner I got a 6 year (72 month) 100,000 mile warranty, based on my driving habits I should have 90,000 miles on it in 6 years, if I go over 100k miles I will likely lump sum pay off the loan, just for my own personal piece of mind. this second part is opinion/personal preference, as opposed to the first which is science.
 
Good morning!

I'm a newbie here and looking to getting my first 4x4, and yes, 4Runner.

That said, been shopping around, and the dealer quoted me 3.9% for a 60/72-term financing plan through Toyota Financial Services (TFS) for a brand new 2018 TRD Off Road Premium. This is in spite of me having very good credit (770+) and a repeat customer with TFS.

Why is it so high? Both my cars (my commuter and my wife's daily driver) were paid with 0.0% with 4-years (ending in March '18) and 5-years' term (ending July '18); while my motorcycle is at 1.9%.

What APR do you have for your 4Runner, assuming you're financing? And if you don't mind - through what bank, credit union, credit provider, etc?

Thanks!!!


_


I just got a 2018 Trd Off Road and they wanted to give me 3.79% 750 Credit which is Tier 1 + through Toyota Financial. I negotiated them down to 3% Flat as I gave 10k down. 4Runner never have any offers, Camry was having a deal for 0.9% when I was getting my runner and the Tacoma and Tundra both had 1.9%.
 
4.9% but more concerned with final #

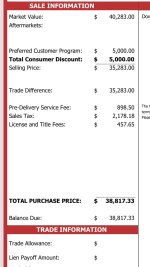
About to pull the plug on a Premium 4x4 (not the TRD model). Been to 3 dealerships local to me and they’re all FOS with their games. I can handle the 4.9 as I’m only 706 credit score. I’v been negotiating down on price as I know they’re going to be profiting heavily on my rate, probably even marking it up some. After researching the TRD & Premium 4x4 models only for the last few months, I get the feeling the South Florida dealers (1)don’t care about the customer at all, & (2) couldn’t care less if you walked away from their shenanigans. Not to hijack your original post. Utbheres an example of sticker vs emailed quote below. No deslership names mentioned. This is on a Premium 4x4. I’m waiting on a TRD quote soon. Looks like Delivery fee charged twice (different amounts) after he offered me $5k discount as its already included in the sticker. What do you guys think?
 

Attachments

  • 8F8EE3A1-44FF-4E3B-927F-26104441E741.jpg
    8F8EE3A1-44FF-4E3B-927F-26104441E741.jpg
    127.4 KB · Views: 220
  • 5FA872BB-76CF-4D1E-A28D-002E6904A732.jpg
    5FA872BB-76CF-4D1E-A28D-002E6904A732.jpg
    108.8 KB · Views: 199
I would strongly encourage you to obtain financing or at a minimum a financing offer from a credit union or bank you already do business with, I got 2.49% and my credit score is only a bit higher than yours. regarding the price, if you've spoken to three dealers near you, I'd call that adequate due diligence, take the offer that is the best deal of the three based on your needs.
 
I ended up with 1.9 for 72 months. I went to my credit union and got this rate and Toyota matched it. It also got me a deal on an extended warranty on the 4R. Credit is score is in the low 800's.

why not support your credit union and finance through them?
 
About to pull the plug on a Premium 4x4 (not the TRD model). Been to 3 dealerships local to me and they’re all FOS with their games. I can handle the 4.9 as I’m only 706 credit score. I’v been negotiating down on price as I know they’re going to be profiting heavily on my rate, probably even marking it up some. After researching the TRD & Premium 4x4 models only for the last few months, I get the feeling the South Florida dealers (1)don’t care about the customer at all, & (2) couldn’t care less if you walked away from their shenanigans. Not to hijack your original post. Utbheres an example of sticker vs emailed quote below. No deslership names mentioned. This is on a Premium 4x4. I’m waiting on a TRD quote soon. Looks like Delivery fee charged twice (different amounts) after he offered me $5k discount as its already included in the sticker. What do you guys think?

toyota isn't going to offer you good financing on the 4runner because they don't need to, sales are good.

with your credit score you should be able to get financing at a much lower rate, you need to check rates at credit unions. PenFed is very easy to deal with and a 60 month loan is 2.999%, you can probably find lower if you do some searching.
 
I am going with my credit union. They've always treated me nicely from day #1...! To get pre-approval for today at 2.25% for 72-months didn't take more than a 10-min phone call. Now, that is SERVICE!!!

Cheers,


_

why not support your credit union and finance through them?

+100 on working with your credit union. My credit union has been phenomenal with everything Ive ever needed from them. Always personal, always available and decisions are made while Im there. No back and forth, follow ups, etc to deal with. Oh yeah, always the best rates too
 
why not support your credit union and finance through them?

Usually I would but I was able to negotiate a better deal using TFS... Also , I was lazy and it was on Dec 31st at the last hour they were open. Most of all because they matched it and I was too lazy ..
 
Hi Guys -

Good morning! And just a few more days before Christmas, and a day more before Star Wars... Hehehe!

Anyways, as posted, I already took delivery of the 2018 4Runner TRD Off Road Premium, and so far, my Wife (it will be her weekday driver, while it will be my weekEND driver) and Kids are loving it!

It the last couple of weekends, had attached a front/rear dashcam (Blackvue dr750s), the rear backup camera override, and some LED accent lighting. This Saturday will be taking it back to the dealer to have the TRD wheels and BF tires installed. Woot...!!!

As a reference for folks, here is what I got:

3ec5cf9668559897df69823df5e1a702.jpg


I have a 772 FICO and had it financed through my local credit union at 2.25% for 78-months (yes, instead of 72). I traded our 2013 Toyota Camry Hybrid XLE for $13K ($3K higher than Carmax, and $2K than KBB Instant Cash Offer), while adding an additional $10K of downpayment.

I added a credit union GAP protection for an additional $349; and a third-party (credit union partner) mechanical repair coverage for 100K-miles/72-months for $903.

Hahaha! The credit union was "selling" their credit protection plan which is an additional $2.7K over the life of the loan; but I told that based on my amortization table, the value of the vehicle (total loss case + GAP) will ALWAYS be more than the balance of the loan even from day #1.

Cheers!!!

PS: Yeah, what really hit me here is the CA sales tax; and that the 4Runner seems to be in demand (with low supply) that some dealers are actually fine putting a mark-up and/or sell at MSRP.


_
 
Last edited:
Hi Guys -

Good morning! And just a few more days before Christmas, and a day more before Star Wars... Hehehe!

Anyways, as posted, I already took delivery of the 2018 4Runner TRD Off Road Premium, and so far, my Wife (it will be her weekday driver, while it will be my weekEND driver) and Kids are loving it!

It the last couple of weekends, had attached a front/rear dashcam (Blackvue dr750s), the rear backup camera override, and some LED accent lighting. This Saturday will be taking it back to the dealer to have the TRD wheels and BF tires installed. Woot...!!!

As a reference for folks, here is what I got:

3ec5cf9668559897df69823df5e1a702.jpg


I have a 772 FICO and had it financed through my local credit union at 2.25% for 78-months (yes, instead of 72). I traded our 2013 Toyota Camry Hybrid XLE for $13K ($3K higher than Carmax, and $2K than KBB Instant Cash Offer), while adding an additional $10K of downpayment.

I added a credit union GAP protection for an additional $349; and a third-party (credit union partner) mechanical repair coverage for 100K-miles/72-months for $903.

Hahaha! The credit union was "selling" their credit protection plan which is an additional $2.7K over the life of the loan; but I told that based on my amortization table, the value of the vehicle (total loss case + GAP) will ALWAYS be more than the balance of the loan even from day #1.

Cheers!!!

PS: Yeah, what really hit me here is the CA sales tax; and that the 4Runner seems to be in demand (with low supply) that some dealers are actually fine putting a mark-up and/or sell at MSRP.


_

so you financed roughly 20k and bought gap insurance? or am I missing something?
 
if it's not too late to sell your mechanical breakdown plan, you can get 100-120k mile toyota platinum coverage for just a few hundred bucks more than that
 
Last edited:
I’m purchasing my TRD off road premium on 12/20. I have excellent credit. Through USAA, I got 2.5 for 72 months. The dealership said they couldn’t match it.
 
I’m purchasing my TRD off road premium on 12/20. I have excellent credit. Through USAA, I got 2.5 for 72 months. The dealership said they couldn’t match it.

That's what I got.. .well 2.49 but really the same, I got it through Service Credit Union right at the dealership, I don't think there's much available less than that, especially with interest rates rising. :reddance:
 
About to pull the plug on a Premium 4x4 (not the TRD model). Been to 3 dealerships local to me and they’re all FOS with their games. I can handle the 4.9 as I’m only 706 credit score. I’v been negotiating down on price as I know they’re going to be profiting heavily on my rate, probably even marking it up some. After researching the TRD & Premium 4x4 models only for the last few months, I get the feeling the South Florida dealers (1)don’t care about the customer at all, & (2) couldn’t care less if you walked away from their shenanigans. Not to hijack your original post. Utbheres an example of sticker vs emailed quote below. No deslership names mentioned. This is on a Premium 4x4. I’m waiting on a TRD quote soon. Looks like Delivery fee charged twice (different amounts) after he offered me $5k discount as its already included in the sticker. What do you guys think?

$700 for oil changes and $400 for floor mats? Nice work...
 
About to pull the plug on a Premium 4x4 (not the TRD model). Been to 3 dealerships local to me and they’re all FOS with their games. I can handle the 4.9 as I’m only 706 credit score. I’v been negotiating down on price as I know they’re going to be profiting heavily on my rate, probably even marking it up some. After researching the TRD & Premium 4x4 models only for the last few months, I get the feeling the South Florida dealers (1)don’t care about the customer at all, & (2) couldn’t care less if you walked away from their shenanigans. Not to hijack your original post. Utbheres an example of sticker vs emailed quote below. No deslership names mentioned. This is on a Premium 4x4. I’m waiting on a TRD quote soon. Looks like Delivery fee charged twice (different amounts) after he offered me $5k discount as its already included in the sticker. What do you guys think?
No surprise, FL let's the crappyest shysters do "business " in the state. Usually, its because they were run out of another. They start at the top with the steaming piles in Tallahassee. There are many things I miss about FL an many, many I don't.

Sent from my SM-G920V using Tapatalk
 

Members online

Forum statistics

Threads
278,316
Messages
3,554,121
Members
248,016
Latest member
Advally Service

Trending content

Back
Top