Insurance Help - Total?

MTB@ATX

New member
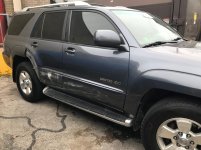
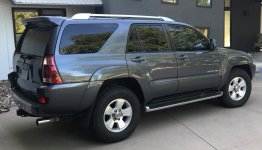
My 2004 Limited V8 with 150,000 got hit on the passenger side this week - old guy coming out of a parking lot. I'm the original owner - 150,000 miles, and 100% stock except for a new Bluetooth radio. Overall excellent condition and all maintenance done religiously. Insurance company wants to total the vehicle as replacing two doors and the running board exceed their estimated value of the vehicle. Of course I'm challenging their value estimates, adding in recent maintenance expenses, recent new tires, etc. but we all know how that goes.
Any other advice? I know I can buy it back, but I don't really want a salvage title for multiple reasons. Thoughts? Project anyone? Before and after pictures attached.
 

Attachments

  • 2004.jpg
    2004.jpg
    134 KB · Views: 622
  • Damage.jpg
    Damage.jpg
    135.1 KB · Views: 575
Register to hide this ad
Find a different Body shop and have them write you a quote. Look for a family owned/small business one. Your insurance can’t make you go to their preferred shop. That’s usually how they total vehicles out. If you’re trying to find a certain value search Craigslist all over the country. Find the highest priced comparable trucks to yours and send it to them. Tell them this is how much it will cost me to get a new one
 
Thanks. I picked the body shop - had prior good experience with them - small family owned. I wouldn't use their big corporate body shop.
I'm scouring listings across the country to provide better comps. They won't let me use CL, but I can use any dealer site for comps - but they want to limit the radius to 150 miles (I'm in TX) which is another BS way they can keep the comps down. As we know on here, there is what a T4R enthusiast would pay and then there is what a non-enthusiast would pay for their high-schooler or whatever. I know I'm too emotionally attached to be objective here, since I bought it new.
 
I have a little experience with this. My boxster needed a bunch of work after a mishap where no body damage was done, but needed mostly suspension work and one wheel. USAA wanted to total it since it was close to their number for a total. They did authorize the repairs eventually.
I think they take current value when not wrecked and assign about 50 percent of repair value to determine whether they will pay for the repair or total it. I would find out those numbers and talk with them once you have done your research.
 
You could always just opt to not go through insurance and find a set of doors and other bits from someone parting out a 4Runner.
 
What are the costs for the repairs and what is the insurance company proposing to give you?

You may want to get an independent appraiser to determine the pre accident value.
 
We are getting closer to having all of the information. I gave them recent expenses plus 10 comps that were more realistic than what they were using and hoping that gets the value up. 4 of their 5 comps were V6’s and mine is a V8 with no adjustment....right. Stay tuned - appreciate the insight from all on here.
 
In Texas, the repairs can go up to 100% of the Actual Cash Value of the vehicle. They are likely using the ACV minus Salvage to determine the repair threshold, but you do not have to accept this as the settlement option.

PM Me and we can chat privately about your situation. I am a licensed insurance adjuster in the State of Texas.

As long as your claim is not with the company I work for, I'm happy to help you resolve your claim.

My advice is always free. I just like to help my T4R brother's out since I've been in the shop for 20 years, and now a Licensed Adjuster since late 2018.
 
The laws and settlement practices vary state to state. I'm happy to provide opinions/thoughts if you wish to send a PM.
 
I worked as an estimator for a high volume insurance shop for 4 months last year. Worst job ever! I went back to restoration work. BUT if the door frame of the vehicle is damaged it will be a total. Replacing that is a very invasive repair. If it really is just a running board, 2 doors and a quarter repair you will be on the edge most likely. If there's no underlying damage I would just buy it back and deal with the salvage title. It's an 04 4Runner it's never going to be a collector car where that black mark on the title will matter that much.
 
Similar thing happened to me last summer. I was in an 04 V8 Sport w/ 190K miles which got hit on the highway from behind by a young girl not paying attention (texting?) and going about 100 MPH. I fought both my and her insurance companies for about 3 months and ended up using hers for a settlement payment. If it was their fault, you should definitely go after both insurance companies as they have different guidelines and payouts. Until you actually settle, with one, there's no issue going after both other than the time you will be fighting them and without a car or driving yours damaged. In my case, I couldn't get either company to fix the car which IMO is the only way to come out of this close to whole and like you I wasn't interested in a savaged title. My insurance, Allstate, would only give me $7K for the car which is a total joke. Hers ended up giving me about $11K and I ended up finding a 14 TEP and spent about $14K to upgrade. The entire experience was awful and I got rid of Allstate as soon as I received payment and got my new insurance set up. I had been a member of Allstate for over 30 years with home, auto and umbrella policies with very few claims and they treated me like crap. In fact, I believe the entire industry now is based on never fixing your car and giving you nothing for it. They've lobbied the state governments and the laws are now set up for them to be judge, jury and executioner. I was advised several times through the process that the only way you come out ahead with this type of situation is if you claim injury of some sort. Otherwise, you're at their mercy.
 
The other driver’s insurance company agreed to open up the comparable vehicle range to nationwide to get more V8 Limited 4WD but it didn’t change the numbers significantly. There were insistent it was to be totaled.

I’ve now filed with my insurance carrier - hoping they are more likely to repair it as the damage-to-ACV ratio is only 25% to 50% depending on who’s repair estimate you use. The pillar is not damaged. Drives straight. Both doors are fully operational. Should know the outcome early next week.
Thanks all for the information and insight.
 
UPDATE: Parts are on order and my insurance company is fixing the vehicle. $2,100 total repair estimate or something in that range. Hopefully I will get my $1k deductible back after they fight with the other insurance company. Just happy to save the truck. Still can’t believe the other insurance company wanted to total it out with $2k in repairs.
 
Does anyone go with an agreed value? I would assume this whole mess would be infinitely more complicated if you had a lift kit, snorkel, winch, plate bumpers etc all fitted. The vehicle could be built up to be 3x or 4x the value of what any "book value" would be and yet the insurance company will give you pennies on the dollar.

I am looking at ways to insure my truck so that this sort of thing does not happen....any words of wisdom?
 
Stated Value vs Guaranteed Value

Hagerty explains the difference between agreed vs stated value.

Agreed Value is more expensive to insure, because they will pay out whatever you insured the car for.

Stated Value is cheaper, typically used on more expensive cars to provide some protection. You could insure the car for 60k, buy if the market says its worth 30k, thats all you get.

Just get Accessory Coverage on your standard policy. 3000 bucks is like 8 bucks a month with most company, and the value of your accessories is covered at replacement cost.
 
Does anyone go with an agreed value? I would assume this whole mess would be infinitely more complicated if you had a lift kit, snorkel, winch, plate bumpers etc all fitted. The vehicle could be built up to be 3x or 4x the value of what any "book value" would be and yet the insurance company will give you pennies on the dollar.

I am looking at ways to insure my truck so that this sort of thing does not happen....any words of wisdom?

Call your carrier. Insurance coverage is as unique as snowflakes.
 

Members online

Forum statistics

Threads
278,307
Messages
3,554,050
Members
248,016
Latest member
Advally Service

Trending content

Back
Top