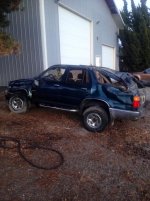
At what point do they total your 4Runner?

Frontier719

New member
Welp, the inevitable happened today. Some knucklehead sideswiped me coming home from work today.

The damage doesn't look too terrible. Broken mirror, scrapes and bumps the length of the driver's side but no big dents or creases. Tore off my mud flap and dented the rear bumper. He hit my rear tire pretty hard and the wheel looks bowed in a little. Hard to get pics at night but some coming tomorrow.

From those of you who have had an accident in a high mileage 4runner, what dollar amount of damage have the insurance companies written it off?
 
Last edited:
Register to hide this ad
The insurance threshold is something like 65-75% of the value of the vehicle. And, at least in my area, the value of these have dropped recently so it doesn't take much to total them. You can get quotes from different shops if you want to try to save it from being a salvage title. But now that these are getting to be 20 years old the insurance companies don't care as much.
 
Honestly it depends. 60-75% is a bit high I believe. Different companies have different standards. I think it's closer to 50%.

Regardless, if they total it out and you want to keep it, that's fine. But, don't let them screw you on for the salvage value of your vehicle (the higher this value, the more they take out of your check). So, call around junk yards and get quotes for your 4Runner. Describe the condition. 3 quotes should be sufficient. Average them out and let the adjuster know you got quotes.

I kept my 97 after a total loss. Originally I was given salvage value of $1,700. Once I told the adjuster what my quotes were he knocked it down to $500 and had no problem negotiating when he saw I did a little homework.

It helps I work in insurance.

Edit: I bought my 97 for $4,500. Got $5,500 for the total loss then sold it 2 years later with salvage title for $3,000. Not too shabby for a 2wd.
 
Honestly it depends. 60-75% is a bit high I believe. Different companies have different standards. I think it's closer to 50%

It's different between companies. When I rolled my first 4Runner the insurance adjuster said he had to reach 70% of the value. $16k in damages and it was valued at $10.5k in 2013(I bought this one back in 2016). Then my second 4Runner was hit in front of my mom's house on Christmas Eve in 2014 ,totaled of course, it was valued at $7500 and had $6500 in damages. If I remember right the threshold for this company was 65%. I bought another 4Runner last year and I knew I would have to get a salvage title for it since it hit a median. I did have to hit 50% of its value which wasn't hard.
 
I t-boned a van that pulled out in front of me and damaged my front bumper and grill. They totaled my 00' limited because the cost to replace the bumper was more then they wanted to invest into it so it got totaled and I got paid the value. Still drive it everyday since, still missing a bumper.

Sent from my SM-G930V using Tapatalk
 
It actually varies state-by-state, but the payout threshold can be as high as 100% of current estimated value. Some states also use a formula of:

If salvage value + repair costs are greater than 80% of vehicle value, they will just salvage it and pay you.

But, they also use different formulae the determine actual, replacement, and salvage values, so it will be tough to estimate what you might get or if they will total.

I dug into this a bit when my wife's first 2016 TRDP was totaled... you'd be amazed to know that the salvage value on it was $19k lol.

Total-loss thresholds by state | CarInsurance.com
 
You can try a Google search for "total loss requirements by state". Insurance companies don't set the requirements for total loss claims; they are set by each state's insurance laws.

Many states generally have an age/percentage requirement (i.e. a certain percentage if it's 7-model years old or newer will result in a total loss, while anything over 7-model years old can be repaired up to 100% of the vehicle's actual cash value at the time of the loss).

There are ways to create a "constructive" total loss, but that usually involved water damage, electronics/wiring, etc.

But you'll need to search out your state's total loss laws to know for sure.
 
Now that I got it home in the garage and took a harder look, I think it's really not that bad. The scrapes are all surface and don't look like they go into the paint at all. I bet some rubbing compound will take them out. Unfortunately they go the length of the car.

The rear bumper has a nice crease but it's not bad and probably won't be too noticeable with some chrome polish.

The only replacement parts it needs are a mirror and a mud flap and hopefully just an alignment. Or i might just take the other mud flap off and make it even.

Of course use the insurance money for an ARB bumper and a light bar though
 
You can get quotes from different shops if you want to try to save it from being a salvage title. But now that these are getting to be 20 years old the insurance companies don't care as much.
Unless things have changed here in the last few years, the salvage title rule only applies to vehicles 5 years old and newer at the time of being totalled in CO. Older than that and it could be totalled and bought back and repaired with a clean title.
 
Unless things have changed here in the last few years, the salvage title rule only applies to vehicles 5 years old and newer at the time of being totalled in CO. Older than that and it could be totalled and bought back and repaired with a clean title.

Ya i live in Alaska now so who knows
 
Answer is state specific. Be careful - in some states, if the damage exceeds a certain amount, it will be reported (must be reported) to the state who will issue certain titles (i.e., total loss vehicle title).

Example: Florida, if the damage exceeds 80% FMV, it'll be a total loss, but you can walk. If, however, it exceeds 100% FMV, then it must be reported and a total loss vehicle title will be issued (uninsurable, etc).


Edit: Appears Alaska is a TLF state (cost of repairs + salvage > actual cash value). I've no experience with that...
 
Last edited:
Yesterday driving home in bumper to bumper rush hour traffic downtown I heard an ambulance behind me somewhere. Then the distinctive "thud". I knew exactly what happened!!! Some guy moved to give the ambulance space and he hit a Tesla zooming by in the car pool lane!!! That will be a total loss, no one here can fix Teslas so even a dented fender is a total loss for the vehicle.
 
I've totaled two and bought them back...and drove them for years. Post up some pics. This was the second time for this one....it was not fixable. Only liability Ins. because I didn't fix it from the first time. Tried to keep it...but the wife drew the line. Would not have bothered me one bit to drive it. Nothing gets fixed anymore...we live in a disposable world. Total that ***** out...buy it back for $7-800 and drive it another 20 years!!
 

Attachments

  • FullSizeRender(63).jpg
    FullSizeRender(63).jpg
    135.2 KB · Views: 1,768
Repair costs are simple, you get quotes, you get the work done, insurance company pays -- done deal.
But when it comes to "totaling" and determining value, it's a completely different set of rules when you're dealing with someone else's insurance vs your own. With your company, you have a contract (the policy) that specifies an agreed upon value of the vehicle, and what they will pay. In an instance such as this -- where you're not at fault, and your dealing with the other driver's insurance -- you have no agreed upon max value. If the KBB value of your vehicle is $3K, but the going rate in your area for a comparably equipped vehicle in comparable condition is $6K, then they owe you $6K. You'll need to provide proof of that inflated value via CL ads, dealer quotes, etc., but it's their responsibility to make you whole -- whatever that takes. What they need to do is restore your vehicle to the condition it was in before their client damaged it. Or they need to replace your vehicle with one comparable to the one you were driving when their client destroyed it.

BTW, they can't "total" your vehicle and take possession of it without your consent.
 
Unless things have changed here in the last few years, the salvage title rule only applies to vehicles 5 years old and newer at the time of being totalled in CO. Older than that and it could be totalled and bought back and repaired with a clean title.

I was required to get my 98 a salvage title otherwise I couldn't title it at all. That's what the DMV made me do which of course was a long and dumb process.
 
This is always on the back of my mind. Unfortunately I live in Miami and about 86% of the people are completely brainless. You can count on barely avoiding an accident during the majority of your daily driving here.

I try to be optimistic, but I know it's just a matter of time.
 
Frontier719 - buy your Gen3 back...it will be a good & cheap DD'er or a $$ maker.
- good reason to not hand over the ownership to quick...might get lucky and keep the title clean, part of the negotiations
- another lesson learned, have tow truck drop off your totaled vehicle in your driveway / avoid storage-compound fees

My brother driving his 2000 Jeep TJ, had a dump truck run a stop sign.
- he still hit the truck wheel at 20 mph, on front corner of his Jeep frame
- frame was bent, and Insurance adjuster totaled it
- they wanted to pay out $9,000 settlement & auction off his salvaged Jeep
- my brother strongly negotiated $11,000 cash
- he never gave up his ownership, and bought Jeep back at cheap Salvage value...probably around $1,500
- brother insisted his Jeep ownership would not be branded & it wasn't....accident kept off CarFax, so clear title intact
- he paid the tow free and a week of storage fees & got his TJ back

My brothers 2 friends, both do excellent body work part time, & one has 30 years experience as a Master frame straightener.
- the Jeep took 26 hours combined labour, to pull frame lazor straight...in a back yard restoration shop
- I sourced parts from a local wrecker
- brother sourced new sheet metal, and misc. odds and ends
All said and done, the Jeep Wrangler was fixed with perfect factory gaps & a final front end alignment confirmed specs.
- all said & done, my brother pocketed half of the $11,000...5 years later, the Jeep is still a very nice & dependable ride

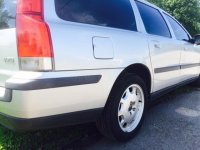
My wife was side swiped by a side mirror of another van...on her former Volvo v70 wagon.
- other lady was 100% at fault & wanted to keep her record clean
- licensed body shop quoted $1,375 for repairs...lady paid me $800 cash
I hand polished the door & quarter panel paint myself...black mark removed, 4 ft. long above fuel filler door
Passenger door dent was fixed (by a Master) without harming paint, for $100...repaired in my driveway, was a $700 profit.
 

Attachments

  • volvoV701.jpg
    volvoV701.jpg
    30.8 KB · Views: 189
Last edited:
I was required to get my 98 a salvage title otherwise I couldn't title it at all. That's what the DMV made me do which of course was a long and dumb process.

In Colorado? I had to do it after I bought back my motorcycle that got totalled out. The county clerk explained it only applied to five model years and newer, and because of that I had to stamp "rebuilt from salvage" on the frame and trailer it to the state patrol HQ to get inspected for roadworthiness.
 

Members online

Forum statistics

Threads
278,309
Messages
3,554,075
Members
248,016
Latest member
Advally Service

Trending content

Back
Top