I will add a couple things in the form of "framing" some of the things already posted.
First, the Personal Auto policy wording (named exclusion) basically "covers" that which is not excluded so, get your law degree out and dust it off OR contact your agent and ask.
That said, follow it with an email stating " Based on our recent discussion, am I correct that the following IS covered......If I am in error please respond otherwise....."
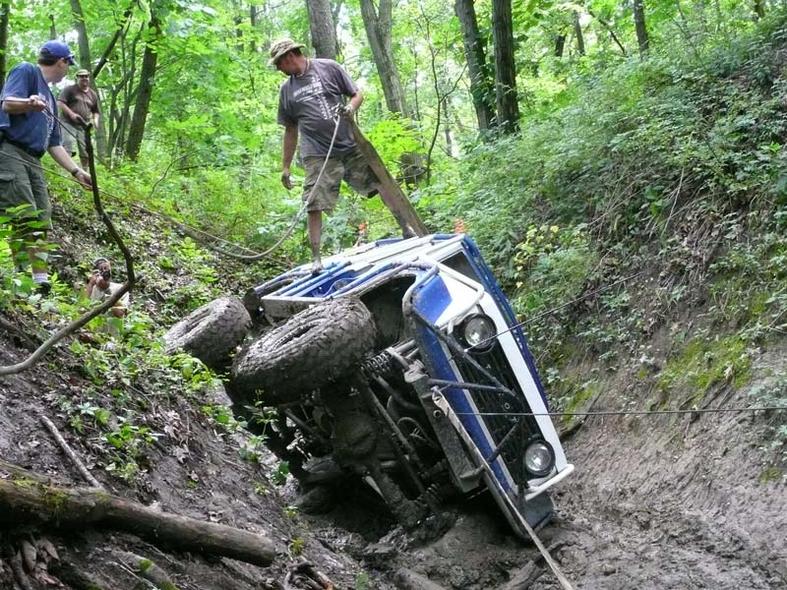
"Upset" or "Rollover" is a physical damage coverage under the comprehensive portion of the policy. Where you want to zero in on is any exclusion that references "Intentional usage, Unimproved road surface, etc" It will vary by company and state so that is why you want to know first and get it in writing (email) BEFORE anything happens.
Now, you will hear people say (not here of course) that IF something happens just tow the rig to a place near a road and say it happened there.
DO NOT do this. Claim Fraud is a very serious offense and one that can lead to serious consequences far more serious than an Oh $h!t rollover.
Just cautioning in general, no inference to be drawn that I would think anyone would consider such a thing.
That's about it. None of my post was or is to be considered "Advice" of any kind nor is it a substitute for researching matters of a local, personal or general nature.
Good Luck.