
Help! insurance wants to write off my perfectly good 4Runner

angela

New member
My brother was driving our 2001 4Runner last week and was in a not-at-fault accident. He was hit in the back and now the insurance company is deeming it a total loss. The first offer they're giving us is 8400 tax-in (We live in the GTA area, southern Ontario). There is no brand applied to it, so it is not a salvage vehicle or un-driveable.

The repair is est. to be at 6600$, and if we choose to have it repaired, the insurance company is giving us the first offer amount minus the tax, which would sit at about 7300.

I've done a bit of research on how to handle claims like this, but I know for a fact that my car is worth more than that. My dad has taken perfect care of it since we've had it (2004). There is no rust on it and only has 160,000 km on it for a 2001 vehicle. It was in an accident last year but we were not at fault, and we had it repaired and it was beautiful. The exterior is in great shape while it drives as it did the day we got it.

I have a copy of the repair estimate and the insurance documents claiming it is a total loss. I want my vehicle back and repaired, but I believe it's worth more money. I know this car is worth more than they are saying. Any advice dear forum? You guys know this car the best. Thank you :)
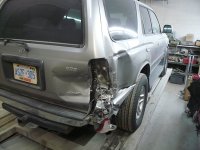
 

Attachments

  • th_1292395551_th_221f76a1b939b12fc6d0c11d87aa7bf5.jpg
    th_1292395551_th_221f76a1b939b12fc6d0c11d87aa7bf5.jpg
    135.5 KB · Views: 1,684
Register to hide this ad
Total loss is typically when repair costs exceed 51% of the value of the vehicle. If you got an estimate of $6600, that means the vehicle would have to be worth more than $13,200... that doesn't seem likely for an '01.
 
First off welcome to T4R! That's a nice ding. I'd leave it, it adds character! I saw that the repair cost was $6600 before I saw the pic and was ready to see a bent frame or rolled over. Heck, down here you can buy a real nice 4Runner for that much $. If they total it out, let me know which junk yard they take it to! Insurrance companies can be a pain. My buddy was rear ended in a 05 Avalanch by a Camry and it bent his frame and drive shaft, cracked his rear end and screwed up the bed. Just one look says "TOTALED". Nope they paid to have it dropped on a new chassis. He was looking forward to getting a new car, ohh well.
 
Maybe I don't understand, you say the insurance company will give you 7300 if you want to repair it, which would cost 6600? I don't see the problem with that. Am I reading this wrong?
 
Since you are not at fault, they should be at your mercy (other drivers insurance im assuming).

I would recomend going on auto trader/cars.com etc , and find a few 4runners with similar options and milage. Print out the adds and get them to the insurance agent dealing with your case, because I think they will be much higher then 7,300 .

If you want to keep the truck I would demand a repair as their only option, Maybe even sugest that your not affraid to hire a attorney.


Also someone else posted above about having them total the truck out, while you buy it back for a small amount . Ive heard about this often but have never personally done it. But its something to look into .
 
Being a Canadian also I know everything up here is more expensive than our brothers to the south. The $6600 repair estimate doesn't seem out of line (My brother in law just had $10K+ in repairs to his 05 Frontier just from a deer hit). I did a search in Alberta of 01 T4R's and there weren't many, ranging from $8-10K. Generally speaking Ontario is usually cheaper for vehicles than here so I wouldn't say they're too far out of line with their offer (sorry) but always haggle with them. You should be able to get more regardless. From the examples I seen I'd say yours in it's condition and km's would be more towards the $10K range.

I would feel the same way if it were my truck. I don't quite understand the offers they're giving you, but if you feel that you want to keep it for a long time yet I would seriously consider keeping it and having the repairs done. Being that it would probably have a salvage title (if they paid you out for it from what i understand) after it would be a bit harder to sell after so that's why I'd only consider if I were going to keep it long term. Short term might not be worth the hassle.
 
Maybe I don't understand, you say the insurance company will give you 7300 if you want to repair it, which would cost 6600? I don't see the problem with that. Am I reading this wrong?

The estimates never cover the actual cost of repair, they are always something like 20% below actual repair cost. They do this the prevent people from pocketing the repair check. Estimating low encourages people to actually get it fixed, where the insurance company pays the autobody shop directly. At least that is how it work in the US.

Yeah, if you weren't at fault, then why is your insurance even involved. Does Canada do car insurance liability differently? The other guy's insurance should pay the repair shop directly, and pay everything. It isn't a negotiable amount, the autobody shop bills the insurance company directly.

Assuming things are significantly different in Canada, it sound like the insurance co is trying to snowball you.

Is this your insurance, or the other guy's insurance?
 
One thing I've learned from dealing with/observing others deal with insurance companies is to NEVER accept their first offer. Looking up what other comparables are selling for as well as getting a few "book values" would be a good place to start.

My sister was t-boned in her Camry a few years back and the insurance offered something around $6,500. After my mom went back and forth with them a few times they ended up giving $8,000. Again, don't take their first offer!

One thing to remember in all fairness you should be given enough to replace your vehicle with an equal in the event they total it. If their offer cannot buy you an equal, it's not enough. That's their responsibility.

GOOD LUCK!
 
Maybe I don't understand, you say the insurance company will give you 7300 if you want to repair it, which would cost 6600? I don't see the problem with that. Am I reading this wrong?

If this is what she was saying (which is how I read it too), the problem is it would be a salvage title after that and the resale would be less than half of a clean title's value.
 
Yeah, if you weren't at fault, then why is your insurance even involved. Does Canada do car insurance liability differently? The other guy's insurance should pay the repair shop directly, and pay everything. It isn't a negotiable amount, the autobody shop bills the insurance company directly.

Assuming things are significantly different in Canada, it sound like the insurance co is trying to snowball you.

Is this your insurance, or the other guy's insurance?

I think it is different in Canada; I'm dealing with my insurance company directly, although it does make more sense for the other guy's insurance to pay for it, right? It's a little confusing.

Thanks everyone for your input. I have done research on the value of the car and have gone over their sampling in regards to the figure they gave me. Of course it's really low, they want to save money, and looking at the sample vehicles they gave, they were all the lowest, cheapest ads for people who just want to make a quick buck, and not anything like our truck (they avoided the highest priced ads).

And I am definitely going to question the 'condition' of my vehicle stated in the report, they've written nonsense about damage to the interior and rips and stains and smells of smoke... like really? No one smokes in our family and they're just writing BS to devalue the truck.

And to clarify, I am able to keep it, they would just give me the write-off amount minus the taxes, which I guess is the same thing in most write-off scenarios where you can buy back the truck for just the taxes amount--so in this case, just under a 1000.

I'm just glad it's not branded as salvage... that would've sucked.
 
I believe that here in Ontario, Canada, No fault accidents work this way:

If nobody is at fault, both insurances deal with their customer. Your insurance deals with you, his (I'm assuming it was a he??) deals with him.

If he would have been at fault, than his insurance would cover you and him, vice versa if you were at fault.

At the end of the day, Insurance companies are obviously only in it for the money. They don't care about you, and will give you the lowest price possible in order to make a buck. They'll offer to buy the truck off of you for cheap, you'll get screwed, and have to buy a truck that is worth less money. They'll sell your truck to a salvage yard, or autobody repair shop that also sells cars, and the truck will be back on the road!

That being said, I've bought a car from an Autobody repair shop that had a salvaged title, paid $6800.00 for 95 Chevy Monte Carlo with 147000km on it. I had that car for 6 years and then sold it for $2000.00! The seller told me it was a write-off because the airbags went off, and the repairs were extensive. This was the same scenerio you are depicting......previous owner got screwed, insurance company made some money selling the wreck, the repair shop fixed the wreck and made even more money.....previous owner ended up buying a lesser car, or had to pay more money out of pocket just to replace the car he or she had!

CROOKS!:sniper:
 
You can negotiate the value of the vehicle. Negotiate the buy back amount. Buy it back. Have it repaired. And you may or may not have a salvage title. I've gone this exact route over 2 years ago with my 4Runner (I held the title). To negotiate the price you will need to get KBB and NADA values for both private party and retail. And as someone already mentioned, find ads for comparable vehicles in your area, list the source and contact number, then total up median and mean prices. CCC Valuescope is absolute BS and was probably the service used to assign a value to your vehicle. Good Luck!
 
No way it costs 6600 to repair that damage. I rolled my 4runner on the right side, which pushed in the left rear of the body. The damage was a lot worse than your accident. The insurance company estimated $8k+ in damage. I told them to go **** themselves. I took it to a friend of mine's body shop and he was able to put it on his frame machine and pull the body straight out, which took out most of the dents. He had to put a little bit of bondo on the top right quarter panel but thats it. It cost me $3k and you can't tell the truck has ever been in a accident.

I would think that if you took it to a body shop where you had some kind of connection you could probably get it fixed for 1500-2k. I would negotiate the hell out of the insurance company to get them to total the truck out for the most you can get out of them. Then buy the truck back from them for pennies on the dollar, and then take it to get it repaired. You are then left with a cleanly repaired 4Runner and cash in your pocket. If you are planning on keeping the truck for a lot longer this plan has alot of pluses.
 
Value is determined by the valuation software used by the insurance company. It's based on condition of the vehicle, cars sold in your area, etc. It can be very accurate, but it depends on entering the correct info into the software. Bad data, back evaluation.

You have a few options depending on your local laws:

1. Take the money and run
2. Buy the car back and fix it
3. Get a 3rd party valuation

On #3, there are companies that can provide this service and handle the discussions with the insurance company--for a fee.
 
be sure that you aren't filing anything through your own company if it wasn't your fault. the only thing that is gonna do is raise your rates (regardless of who's fault it was because your insurance provider will file it under "collision", which is always considered YOUR fault. If you are having issues and you dont agree with what the other companies adjuster is presenting, request to speak to their supervisor. if that doesn't work, ask for the supervisor's supervisor. if that doesn't work, consult your local insurance commissioner. I know you are in Canada, but the insurance company i work for is up there too. I'm sure the rules/regs cant be too different.
 
My brother was driving our 2001 4Runner last week and was in a not-at-fault accident. He was hit in the back and now the insurance company is deeming it a total loss. The first offer they're giving us is 8400 tax-in (We live in the GTA area, southern Ontario). There is no brand applied to it, so it is not a salvage vehicle or un-driveable.

The repair is est. to be at 6600$, and if we choose to have it repaired, the insurance company is giving us the first offer amount minus the tax, which would sit at about 7300.

I've done a bit of research on how to handle claims like this, but I know for a fact that my car is worth more than that. My dad has taken perfect care of it since we've had it (2004). There is no rust on it and only has 160,000 km on it for a 2001 vehicle. It was in an accident last year but we were not at fault, and we had it repaired and it was beautiful. The exterior is in great shape while it drives as it did the day we got it.

I have a copy of the repair estimate and the insurance documents claiming it is a total loss. I want my vehicle back and repaired, but I believe it's worth more money. I know this car is worth more than they are saying. Any advice dear forum? You guys know this car the best. Thank you :)

Get yourself 3 independent estimates. Tell the shops that you plan to not use your insurance so they do not jack up the price. Take the estimates to your insurance company (assuming they are less). This way you know you got the best deal possible.

Reason for getting a low estimate is so they do not total your car... since you say you want it repaired. Otherwise if you want money... get the 3 estimates and tell the shop you are going through insurance, and they may charge a bit more. Pay cash vs. check from insurance company... good luck!
 
Last edited:
be sure that you aren't filing anything through your own company if it wasn't your fault. the only thing that is gonna do is raise your rates (regardless of who's fault it was because your insurance provider will file it under "collision", which is always considered YOUR fault. If you are having issues and you dont agree with what the other companies adjuster is presenting, request to speak to their supervisor. if that doesn't work, ask for the supervisor's supervisor. if that doesn't work, consult your local insurance commissioner. I know you are in Canada, but the insurance company i work for is up there too. I'm sure the rules/regs cant be too different.

Ontario has a "no fault" insurance system where each company handles claims from their own policy holders so you have to deal with only your own insurer. The other insurance company doesn't and can't deal with you. The "at fault" determination in a collison affects your rating for future insurance premiums.

To the OP. This wasn't your fault so take doubleA's and others advice. Get repair estimates and replacement values to build your case. Settle for more than the repairs will cost and buy back the truck, salvage (branded) title or not, if you intend to repair and keep it. Sounds like you are happy with the previous repair. Get an honest opinion from that shop if it's someone you know and can trust.
 
Last edited:
Ontario has a "no fault" insurance system where each company handles claims from their own policy holders so you have to deal with only your own insurer. The other insurance company doesn't and can't deal with you. The "at fault" determination in a collison affects your rating for future insurance premiums.

well aint that just a sh!tty situation. sometimes it works out in your own favor. sometimes not i suppose. good luck with your claim.
 
Last edited:

Members online

Forum statistics

Threads
278,316
Messages
3,554,120
Members
248,016
Latest member
Advally Service

Trending content

Back
Top